- Dexory, of Wallingford in Oxfordshire, builds robots that scan warehouse racking and sells the data. Its revenue was £3.6m in the year to March 2025, up from £0.6m.
- On 1 October 2024 it announced an "$80 million Series B" of equity and growth debt, led by DTCP.
- The filings show three layers: about $49.5m of new preferred shares at $38.012 each; a £10m loan facility from Bootstrap Europe at a fixed 10%, with warrants and a further £15m commitment; and about $1m of shares sold by each of two founders.
- The first Series B shares were issued on 26 June 2024, three months before the announcement. Money kept arriving until 30 December.
- A year later the company raised $165m more: $100m of equity at $46.97 a share, led by Eurazeo, and £21m of 9% secured loan notes.
The company
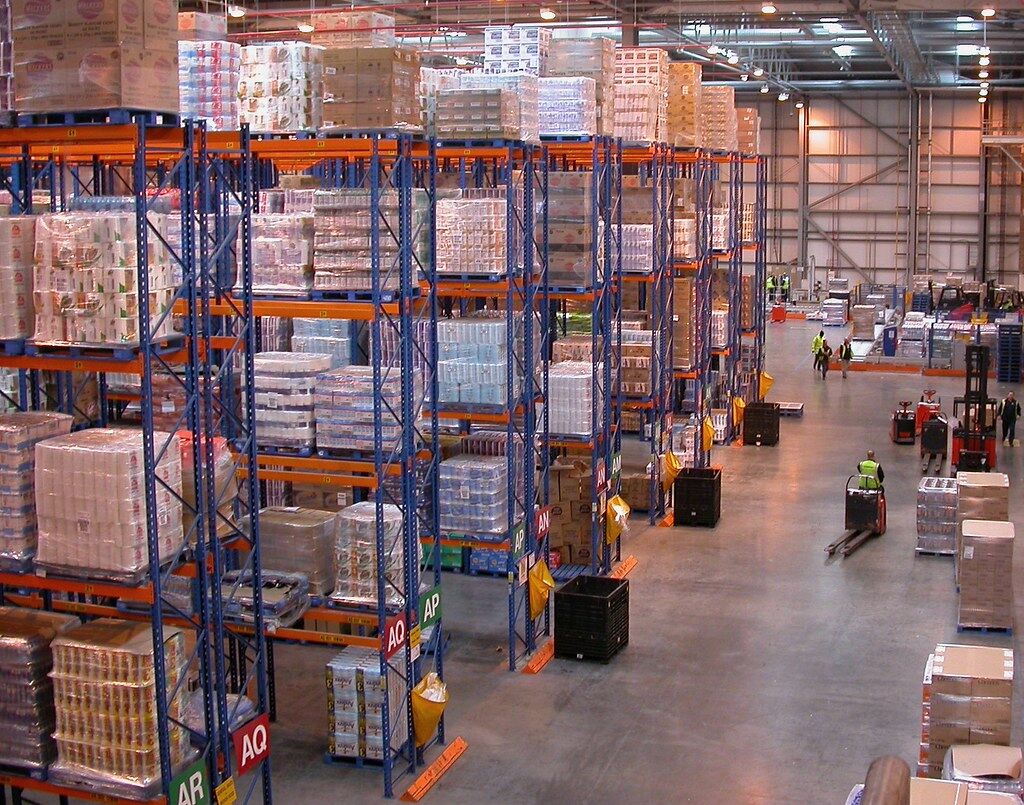
Dexory makes a tall wheeled robot that drives the aisles of a warehouse at night, scanning every pallet location up to 12 metres high. The scans feed a software platform, DexoryView, that tells the warehouse what is where, what is missing and what is in the wrong place.5 The company designs and builds the robots itself in Wallingford, Oxfordshire.
It took a long road to get there. The company was incorporated in February 2015 as Botz&Us, to put robots in airports and shops. It turned to logistics during the pandemic. "For the first five years, we bootstrapped the company, securing over €5 million in public funding before raising any private investment," the chief executive, Andrei Danescu, said in 2025.9 The warehouse product launched in 2022.
Then it grew fast. Revenue in the year to March 2025 was £3.6m, almost six times the year before, mostly from subscriptions. The group lost £21.9m that year, much of it building robots that it owns and deploys at customers' sites, and held £20.5m of cash at the year end.4 Its customers include GXO, Maersk, DB Schenker, GE Appliances and Stellantis.
How the money came in before
The share register tells the story of each round. A small seed round in 2020. A $13m seed extension in 2022 led by Lakestar, with Maersk's venture arm investing alongside. A $19m Series A in June 2023 led by Atomico.1 Later that year Schenker Ventures, the venture arm of the logistics group DB Schenker, added "an undisclosed additional investment".11
Two of Dexory's largest customers had become shareholders before its Series B. Danescu's advice to first-time founders, given to UKTN in 2023, was: "make very good friends of your first customers, they will be key to getting any funding in".12
The Series B as announced
On 1 October 2024 Dexory announced "an $80 million Series B funding round … made up of a mix of equity and growth debt". It was "led by DTCP, with participation from Latitude Ventures, Wave-X and Bootstrap Europe, along with existing investors Atomico, Lakestar, Capnamic and several angels from the logistics industry".5 The money was for AI features, a larger team, the US market and more manufacturing space.
The same day, Dexory told UKTN that the round was "70% equity and 30% debt-based".6 Its own accounts, filed eighteen months later, describe "a $65 million Series B funding round led by DTCP which includes a venture debt facility".4
Three descriptions of one round: $80m, 70/30, $65m. The filings let us see what lies beneath them.
Layer one: the preferred shares
The new equity was Series B preferred shares at a price fixed in dollars: $38.012 a share.3 They were issued in four batches.
- June 2024: 991,019 shares at £29.958, the first close, with DTCP's partner joining the board the same day.
- August 2024: 57,464 shares at £29.66.
- October 2024: 122,592 shares to an investment vehicle of Capnamic, an existing seed investor.
- December 2024: 131,537 shares to Elaia, a French investor not named in the announcement.
Together that is 1,302,612 new shares, about £39.0m or $49.5m. The round was signed on 26 June 2024. It was announced on 1 October, after most of the money had arrived, and it kept filling for three months afterwards. That is common. A company announces a round when it is safe to, not when it starts.
The register shows who bought. DTCP, the growth fund that led, holds 526,148 Series B shares, about $20m at the round price. Atomico added about $7.5m, Latitude about $7.0m, Elaia $5.0m, Capnamic $4.7m and Lakestar $4.5m.
The terms in the articles are plain. Each Series B share has a 1x non-participating liquidation preference: on a sale it receives the higher of its $38.012 back or its share as if converted to ordinary shares. It ranks ahead of every earlier class. It is protected against a lower-priced future round by a broad-based weighted average adjustment, the mildest common form.3 These are the standard terms of a well-supported round. Nobody needed to ask for more.
The company did not disclose a valuation. On the shares in issue, ignoring options and warrants, $38.012 a share implies about $108.6m before the money and $158.4m after. That is our arithmetic. The price was 1.41 times the Series A price fifteen months earlier.
Layer two: the growth debt
On 2 August 2024 the company signed a loan agreement with Bootstrap Europe, a London-based lender that calls its product "non-dilutive funding". The accounts give the terms.4
- A £10m facility of secured loan notes, with "an additional £15.0m loan commitment expected to be available at a later date".
- A fixed rate of 10% a year, repaid over 36 months after six months of interest only.
- An arrangement fee of 1% of the commitment, £100,000.
- First-ranking security over all the group's assets, including its intellectual property.2
- 13,889 warrants over Series B shares, at the lower of $38.012 or the next round's price, exercisable for ten years.
"The effective interest rate at inception, reflecting the allocation of proceeds to the warrants and associated fees, is 12.71%," the accounts say. By 31 March 2025 the company had drawn £3.0m of the £10m.
The warrants cover about $0.53m of shares, roughly 5% of the first facility. That is towards the low end of venture debt, where warrant coverage commonly runs from a few per cent to a fifth of the loan.
Most of the debt had not been drawn. On our reading, that is the point. The company was building robots it would own and lease out, a capital-hungry model, and it had just raised $49.5m of equity. The debt was runway: money available if needed, on known terms, at a cost far below the dilution of more equity. Nobody involved has said so.
Layer three: the founders' secondary
The third layer is the one no headline mentioned. On 26 June 2024, the day of the first close, two founders, Andrei Danescu and Adrian Negoita, each transferred 26,307 ordinary shares.1 In September the company filed a notice turning 52,614 ordinary shares into Series B shares. The October confirmation statement shows WaVe-X Holding, the investment arm of the Austrian transport group Walter Group, holding exactly 52,614 Series B shares.10
The founders sold to WaVe-X, and the shares they sold became the senior preferred class. The price is not filed. At the round price it would be almost exactly $1m for each founder.
This structure, a secondary sale converted into new preferred shares, is how growth rounds increasingly let founders take some money off the table. It gives the buyer the same rights as every other Series B investor, and it gives the founders some security after nine years of building. None of the money reaches the company.
Put the three layers together and the round has three kinds of counterparty: funds buying new shares, a lender beside them, and a buyer of the founders' shares.
The headline was $80m. The filings say $49.5m of new equity, a debt line that was mostly undrawn, and $2m of founder liquidity.
Adding it up
New equity of about $49.5m, plus £25m of debt commitments at about $1.28 to the pound, comes to roughly $81.5m. That fits the $80m headline if the whole debt commitment is counted, including the £15m not yet available. It does not fit the 70/30 split the company gave UKTN. The accounts' $65m may count the equity and the first £10m. None of the three is explained anywhere we found.
By March 2025 the company had $49.5m of new equity and £3.0m of drawn debt, about $53m on our arithmetic. The rest of the headline was a promise, or money that went to the founders.
This is normal, and it is worth knowing. A round's headline is a choice. Debt commitments that may never be drawn, secondary sales that bring the company nothing, and money that arrives months later can all be counted in it or not. An investor looking at comparable rounds needs to know which.
What happened next
Twelve months later Dexory announced $165m more. The filings show $100m of Series C equity at $46.974 a share, a 1.24 times step up, led by Eurazeo, whose funds hold about $60m of it. Existing investors DTCP, Atomico, Lakestar, Elaia, Latitude and WaVe-X all followed. Schneider Electric's venture fund appears on the register, though in no announcement we found.1,8
The debt grew too. In November 2025 the company issued £21m of 9% fixed-rate secured loan notes, with Bootstrap Europe as security agent: a point cheaper than the year before.2 In March 2026 the British Business Bank, through British Patient Capital, was reported to have invested £8.5m as part of the Series C.13
The same month DB Schenker, by then owned by DSV, sold all its Series A shares. They were turned into Series C shares, the same mechanism as the founders' secondary.
| Series B, 2024 | Series C, 2025 | |
|---|---|---|
| Announced | 1 October 2024, as $80m | 14 October 2025, as $165m |
| Lead | DTCP, about $20m | Eurazeo, whose funds hold about $60m |
| New preferred equity in the filings | About $49.5m | $100m |
| Price per share | $38.012, 1.41 times the Series A | $46.974, 1.24 times the Series B |
| Ranking | Ahead of every earlier class | Ahead of the Series B |
| Debt beside it | £10m facility at 10% fixed, £15m more later, warrants | £21m of secured loan notes at 9% fixed |
| Shares sold by existing holders | Two founders, to WaVe-X, made Series B | DB Schenker's Series A, made Series C |
| Public money | — | British Patient Capital, £8.5m, reported March 2026 |
| Layer | Amount | Share |
|---|---|---|
| Secured loan notesBootstrap Europe; 10% and 9% fixed; drawn amounts not disclosed; dollars at $1.28 to the pound, our arithmetic | about $40m committed (£10m facility and £21m notes) | 17.7% |
| Series C preferredEurazeo, British Patient Capital, DTCP, Atomico and others; ranks ahead of Series B | about $100m at issue | 44.2% |
| Series B preferredDTCP, Atomico, Latitude, Elaia, Capnamic, Lakestar, WaVe-X | about $51.5m at issue | 22.7% |
| Seed and Series A preferredLakestar, Maersk Growth, Atomico, Capnamic, Kindred and others | about $35m invested | 15.5% |
| Ordinary sharesFounders, staff and early holders | not disclosed | — |
What it teaches
Customers make the best early investors. Maersk and DB Schenker invested before the Series B. A customer who also owns shares is a reference no pitch can match.
A growth round can be three instruments, each priced on its own. Equity for the long-term risk, debt for the predictable part of the spending, and a secondary for the founders. Together they raised the money at less dilution than equity alone.
- Cash to the company
- The new shares brought about $49.5m. The secondary brought the company nothing.
- Little dilution
- The debt dilutes only through its warrants, about $0.53m of shares. The secondary created no new shares.
- Drawn only when needed
- £3.0m of the £10m facility was drawn by March 2025.
- No interest to pay
- The loan notes cost 10% fixed, 12.71% effective with the warrants and fees.
- Money for the founders
- About $1m each, after nine years of building.
The headline is a choice. $80m, $65m and 70/30 described the same round. The filings are the only place to see what was actually raised.
Rounds close before they are announced. The money was signed in June and announced in October. By the time a round is in the news, the investors in it were persuaded months before.
Maersk's venture arm invested in 2022 and Schenker Ventures in 2023, before the Series B. A customer who owns shares is a reference no pitch can match.
A £10m facility at 10% fixed, with warrants over about $0.53m of shares. By March 2025 £3.0m was drawn. On our reading, it was runway on known terms.
Each founder sold about $1m of shares to WaVe-X, and the shares became Series B. The founders took some money off the table; the buyer got the same rights as the other investors.
$80m in the announcement, 70% equity and 30% debt to UKTN, $65m in the accounts. The $80m fits only if £15m of debt not yet available is counted.
In the year to March 2025 the group lost £21.9m on revenue of £3.6m, much of it building robots it owns. It held £20.5m of cash at the year end, before the Series C.
The 2025 loan notes carry 9% fixed, a point below the 2024 facility. Our read: a lender pricing in a year of growth.
The shares were allotted from June 2024 and announced in October. Comparable rounds should be measured on new equity and drawn debt, which only the filings show.
What we do not know
- Why the round was described as $80m, as 70/30, and as $65m.
- The price WaVe-X paid the founders.
- Who received the August 2024 shares.
- How much of the Bootstrap debt has been drawn, and its covenants.
- The valuation on a fully diluted basis.
- The terms of the 2025 warrants, and why the December 2025 security ranks second.
- Who bought DB Schenker's shares.
- Revenue measures beyond turnover: recurring revenue, retention and margins.
Method. The share issues, prices, register, articles and charges are read from Companies House filings for Dexory Limited. The accounts, debentures and articles are scanned images read by optical character recognition, and each figure was checked against a second filing where one existed. Dollar figures for holdings assume each was bought at the round price. Valuations and the reconciliation of the headline are our arithmetic, not company figures. We have not spoken to the company or its investors. Norvian Capital Partners has no relationship with any party in this case.
“The headline was $80m. The filings say $49.5m of new equity, a debt line that was mostly undrawn, and $2m of founder liquidity.”
Sources
- Dexory Limited (09448674): filing history, allotments and confirmation statements, Companies House, accessed 9 September 2026
- Dexory Limited: charges, Companies House, accessed 9 September 2026
- Dexory Limited, Articles of Association adopted with the Series B, Companies House, filed 12 July 2024
- Dexory Limited, group accounts for the year to 31 March 2025, Companies House, filed 31 March 2026
- Dexory secures $80M funding to drive global expansion goals, Dexory, via RoboticsTomorrow, 1 October 2024
- Warehouse robotic firm Dexory closes $60m Series B round, UKTN, 1 October 2024
- Shoosmiths advises DTCP on $80m Series B investment into Dexory, Shoosmiths, 14 November 2024
- Strong customer demand enables Dexory to secure $165M in funding, Dexory, via RoboticsTomorrow, 14 October 2025
- Why hybrid human-robot teams are the future of logistics: Andrei Danescu, Underline Ventures, 4 February 2025
- WaVe-X: Der österreichische Mobility- und Logistik-Investor im Talk, Trending Topics, 8 July 2024
- Dexory announces new investment from Schenker Ventures, Retail Technology Innovation Hub, 20 September 2023
- Dexory founder: Make good friends of your first customers, UKTN, 14 April 2023
- Dexory raises £8.5m to improve inventory accuracy using robots and digital twin, Startup Mag, 26 March 2026
Cite as: “Dexory: what an $80m round is made of”, Norvian Review, 10 September 2026.